Food traceabilityBatch traceability
Batch mass balance: investigate quantity differences with units attached
A mass-balance review compares recorded inputs, outputs, remaining stock, waste and adjustments within a defined scope. Consistent units and clear boundaries matter more than a percentage that conceals estimates or unexplained differences.
At a glance
A mass-balance review compares recorded inputs, outputs, remaining stock, waste and adjustments within a defined scope. Consistent units and clear boundaries matter more than a percentage that conceals estimates or unexplained differences.
Define the decision behind the record
Define the product, period and events included before calculating. Do not add kilograms and units without an explained conversion. Keep estimated amounts identifiable and distinguish production yield from an unexplained recording difference.
Reconcile a defined material and unit before explaining differences
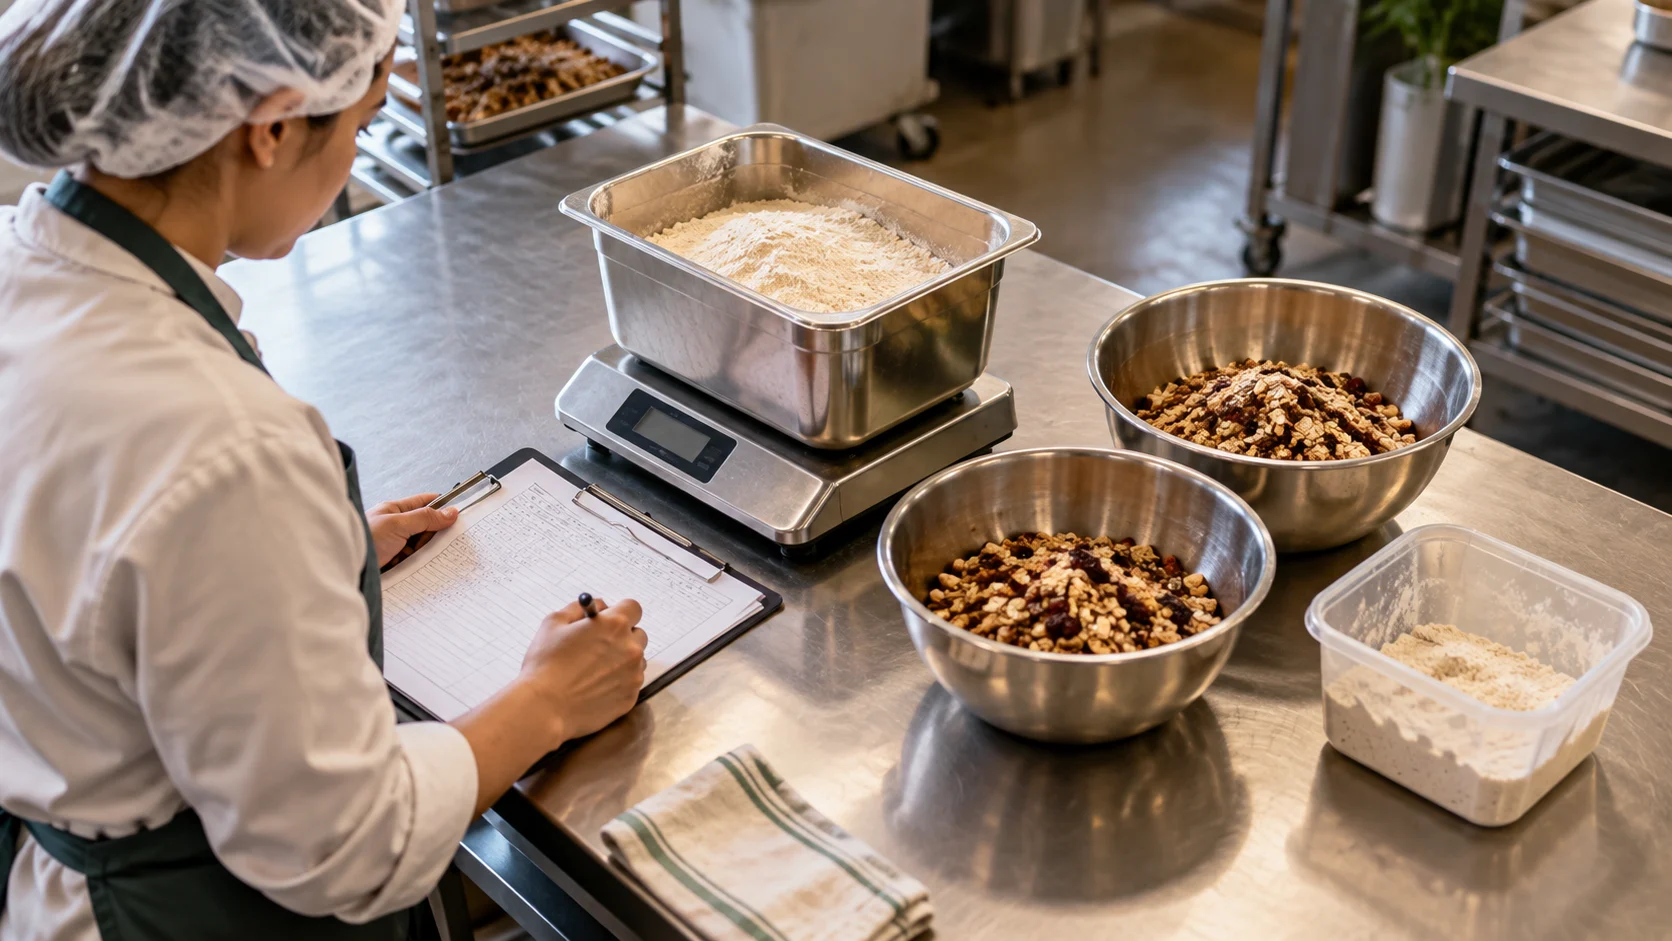
Define the material, lot, period and locations included in the balance. Separate ingredient use from the total output of recipes containing other ingredients. Choose consistent units and identify any conversion, estimate or measurement limitation before comparing quantities from different records.
Combine opening stock, receipts, use, dispatch, losses and authorised adjustments within that boundary. Preserve the actual counts and source references. When the numbers differ, record the discrepancy and investigate missing movements, returns, samples or unit errors rather than entering an unexplained adjustment solely to reach zero.
Review both arithmetic and evidence. A mathematically balanced spreadsheet can still be incomplete if it double-counts a transfer or invents a loss. Test one clean balance and one with an intentionally missing movement. Another reviewer should explain the included quantities and identify the unresolved difference from the source records.
Worked example
A practice traceability exercise accounts for a received ingredient through recorded use, remaining stock and documented loss. A difference remains. The team records the gap, checks the source transactions and assigns follow-up rather than forcing the worksheet to balance.
Build a usable record
Use the fields below to capture the facts needed for this particular decision. Keep the actual observation separate from any later correction or approval.
- Product and review boundary
- Input quantities and units
- Outputs, stock and loss
- Conversions and estimates
- Difference explanation and action
Example record and review decision
Fictional record example: ING-A: 20 kg received, 8 kg used in PREP-1, 6 kg used in PREP-2 and 6 kg remaining; difference 0 kg.
Reconcile one ingredient and unit at a time. Finished recipe output may include other ingredients and is a separate balance.
If 2 kg is unexplained, investigate losses, returns, transfers or missing entries rather than creating a balancing adjustment without evidence.
Test the review, not just the form
Have a second person reproduce the calculation from the source records. They should understand the conversions without guessing. A reconciled total does not by itself prove that all affected product destinations were identified.
A few useful answers
Is a balanced total proof of complete traceability?
No. Check both quantities and the identity relationships connecting receipts, batches and destinations.
Does a zero difference prove complete traceability?
It establishes arithmetic consistency within the chosen inputs, not necessarily that the records are correct or complete. Check movement boundaries, duplicated transfers, units and the evidence behind adjustments as well as the final total.
Sources and further reading
MarkdownExplore starter templates
Start with a useful checklist
English